
MARKET PERSPECTIVE
By J Mulraj
Oct 17-23, 2026
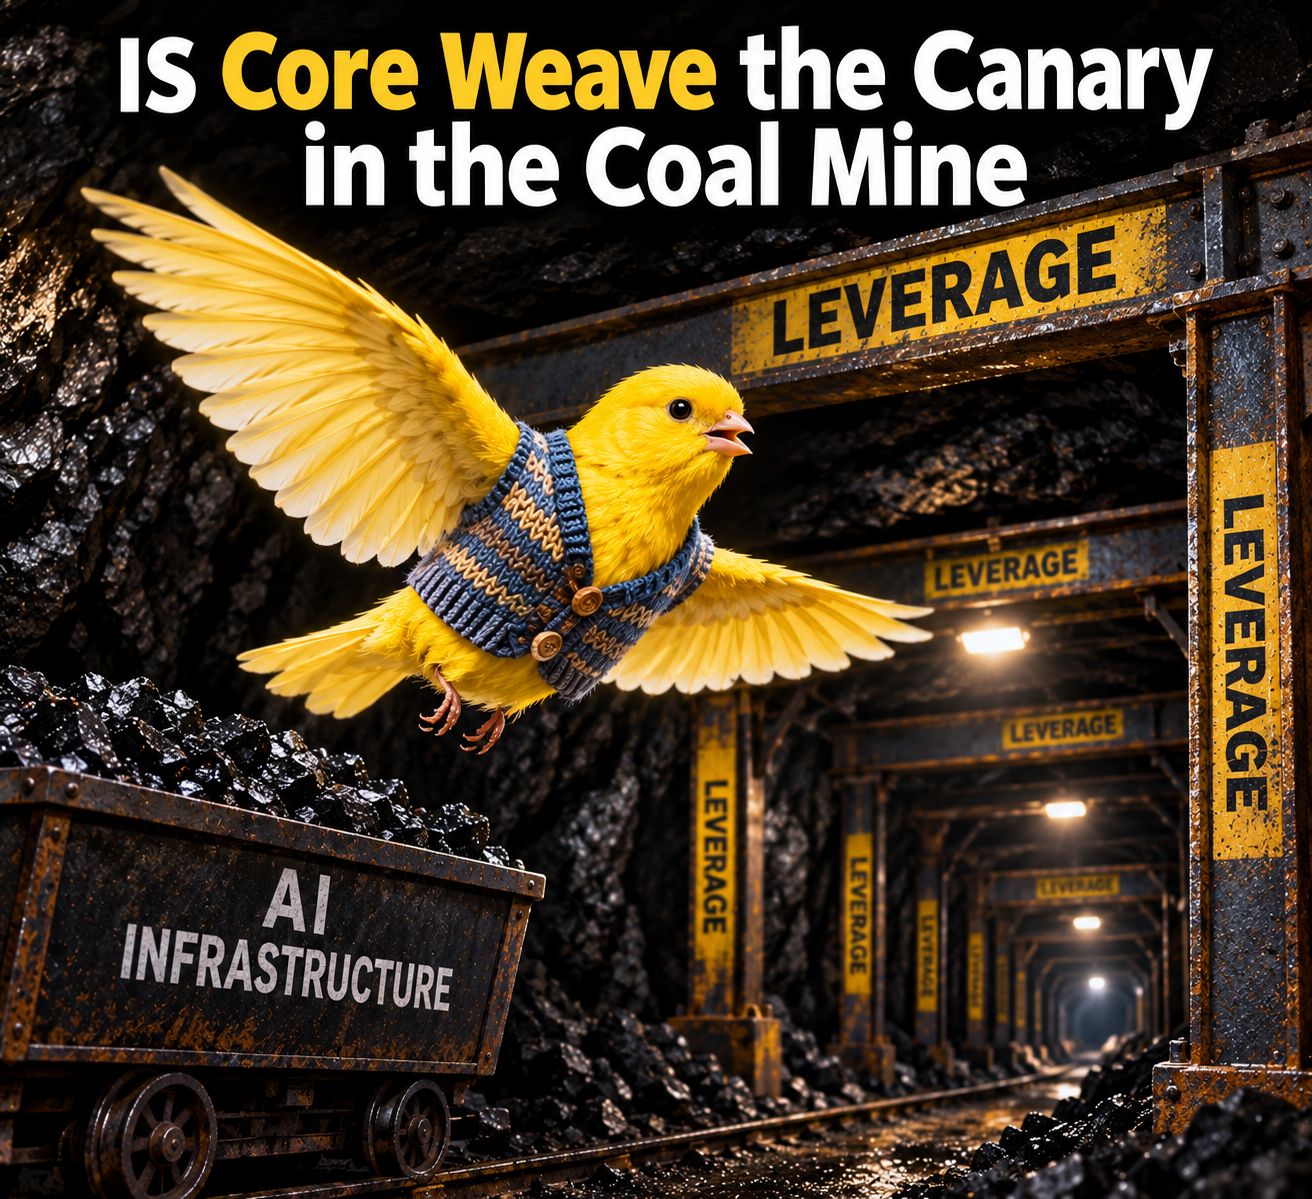
Oh what a tangled web Core Weaves
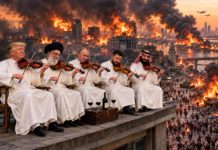
Image created using ChatGPT
CoreWeave (CRWV) is a company that buys huge quantities of specialised AI chips, especially Nvidia GPUs, and builds data centres, then rents the computing power to frontier AI companies, LIKE openAI, Microsoft, Meta and others. Nvidia owns a significant stake in CRWV.
To build its data centres. CRWV has accumulated around $ 50 b. in debt. It has yet to report a profit. Its Q2 results, declared in August, showed a net loss of $ 626 million, thanks entirely to it’s interest outgo of $ 640 million. Its debt situation is so alarming that yield on the bonds issued by it, maturing in 2030, hit 16%. Moreover, its equity crashed after the collapse of the hedge fund Situational Awareness, which had invested heavily in CRWV. The collapse of the fund brought down its stock price from a high of $ 153 to around $60/ share.
The large companies, the hyperscalers, initially used their own cash flows from operations, to build data centres. But the demand is insatiable, and they are increasingly resorting to debt markets to fund the growth. In some cases by using Special Purpose Vehicles to raise debt, thus not reflected in it’s own books.
So investors are wary, and are asking if CoreWeave is the canary, or early warning of disaster, in the AI coal mine.
The AI growth has often been the result of circular financing. For example, Microsoft has invested heavily in OpenAI, which is obligated to spend a significant part of this to buy MS’s Azure cloud computing services to train and run its models. So the capital outflow from MS returns to it as a revenue inflow.
Oh! What a tangled web we weave, when first we practise to deceive!
Such circular financing is at risk of turning into the proverbial house of cards. This poses a huge risk for stock market investors. The fall from peak is the lowest in US stock markets compared to global markets.
In America, the Nasdaq composite is just 4.3% below its peak, the S&P 500 around 1.7% and the DJIA 4.4%.
But other markets are emulating Humpty Dumpty.
Nikkei 225 is 11.4% below its peak, the Hang SENG 14.9%, the Shanghai Composite 10.4%, the BSE Sensex and NIFTY are 13-14%. Only the Footsie is a modest 2.4% below its peak.
So should the CoreWeave canary in the coal mine spook investors, the fall in the US stock market would have a ripple effect.
AI debt issuances have risen to $ 466 b year to date, up from $ 101 b in the same period last year, unnerving investors, who have rushed to buy insurance on the bonds, via credit default swaps.
Last week saw student protests and wanton destruction of public property in France. One of the main, and untackled, problems in France is underfunded pensions, due to adverse demographics due to which there are fewer youth joining the workforce and contributing to the pension pool, and more seniors retiring at age 62 and drawing benefits. Attempts by President Macron, and his predecessors, to raise the retirement age to 64, have met with stiff resistance. The funding of pension shortfalls have led to cuts elsewhere, including education, creating the current wave of student protests.
Other EU countries are in their own, often self inflicted, messes. Germany was the manufacturing powerhouse of Europe and praised for its efficiency and productivity, especially its automotive sector. But, heeding the advice of US Presidents, Germany foolishly suspended supply of Russian cheap oil and gas, to replace it with more expensive options. The additional energy cost destroyed its competitiveness. The oldest automobile manufacturing plant of VW now produces weapons.
Italy is over indebted, and is also suffering public angst and rioting. So are other EU economies.
The root of the problem is that democratic Governments have spent money to solve problems, like pension fund shortage, by resorting to borrowing and not by raising taxes. The latter option reduces the chance of a re-election, the former quietly kicks the can down the road.
We are near the end of that road. The riots are symptomatic of a disgruntled populace now facing their day of reckoning.
The two major wars, Russia-Ukraine and US- Iran, show no signs of ending. Brent crude has gone above $ 110/b. This will fuel inflation, and hence a rise in interest rates to tame it. So more public unrest and riots.
All this is not a healthy diet for a bull.
Last week the BSE Sensex ended at 73153, for a weekly drop of 1606 points.
In interesting news, the Stanford University Global AI Vibrancy ranking, 2024, rates India at #3, ranked after US and China , and above South Korea, UK, Singapore and others. The ranking is based on 7 criteria, comprising R&D, Responsible AI, Economy, Talent, Policy & Governance, Public Opinion and Infrastructure . This is a highly commendable achievement for India.
Another good development is the likely takeover, by Tata Motors, of Ivesco, the largest commercial trucking network in the EU, at an estimated cost of €3.9 b, in an all cash transaction. It currently belongs to the Agnelli family. N Chandrasekharan is expected to be Chairman of Ivesco.
India must focus also on its structural weaknesses. Under a welfare scheme the Government provides subsidised grain to 835 million people, which is 55% of India’s population. The objective is, indeed, laudable. But the question to ask is why, 79 years after Independence, we need to give subsidised grain to more than half the population! This points at weaknesses in our agriculture policy and in the absence of employment opportunities. One of the causes for that is the appalling slowness of the judicial system, with a backlog of pending disputes that is the highest in the world. Such backlog discourages entrepreneurs from investing.
Global events like never ending wars, supply chain disruptions leading to inflation, over indebtedness of nations and social tensions leading to riots, all scream for caution. We are less than a fortnight away from US mid term elections.
Let’s hope that the canary flies away, tweeting softly, and not impacting the coal mine.
—————————————————————-
Comments can be emailed to: jmulraj@asiaconverge.com


COMMENTS